
Lecture
Poisson random measure with intensity measure is a family of random variables defined on some probability space such that 


i) is a Poisson random variable with rate . 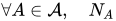

ii) If the sets do not intersect, then the corresponding random variables from i) are mutually independent. 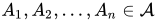
iii) is a measure on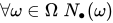

If then satisfies conditions i) –iii). Otherwise, in the case of a finite measure, taking , a Poisson random variable with rate , and , mutually independent random variables with distribution , define , where is a degenerate measure located at . Then will be a Poisson random measure. In the case of non-finiteness, the measure can be obtained from measures constructed above on the parts where is finite. 


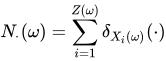


This type of random measure is often used to describe the jumps of random processes, in particular in the Lévy–Itô decomposition of Lévy processes .
The Poisson random measure generalizes to random measures of Poisson type, where the members of the PT family are invariant under restriction to a subspace.
Poisson random measures.(S, B), ξ1,... - i.i.d. with values in S, X is a finite measure on (S, B).
Let us introduce a random process Y ∼ P ois(λ(s)),Үi {ξk}
independentҮ and ξk may take values in different spaces
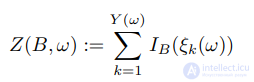
- Poisson random measure

Comments