
Lecture
There are two main approaches to analyzing the organization of industrial
markets: the Harvard school and the Chicago school (analysis from the standpoint of price
theory).
The Harvard paradigm (Fig. 1) was developed by professors of the
Harvard school, E. Mason and J. Bain, in the 1940s and 1950s.
Fig. 1. The Harvard paradigm
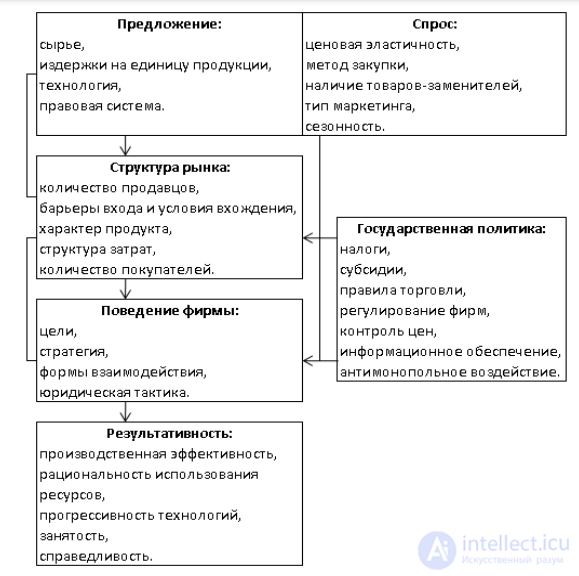
The paradigm was originally oriented toward empirical
research. Bain and Mason put forward the hypothesis that a direct
relationship exists between market structure, firm conduct, and the performance
of the market. The paradigm views the industrial market
(hereinafter IM) as a set of several blocks that interact with
one another and influence one another.
The object of research – the possibility of predicting the parameters
of market performance after analyzing its structure, basic conditions, and
firm conduct. This direction can be called a systemic approach (from the standpoint
of the paradigm known as “structure – conduct –
performance”).
Market structure: market boundaries (product, geographic,
and time), the number of sellers, the number of buyers, the concentration
of sellers and buyers, market power, entry and exit barriers,
and differentiation.
Firm conduct (the set of strategies pursued by firms operating in the
industry): product, pricing, advertising, and innovation strategies, merger
and acquisition strategy, and interaction among firms.
Market performance: market price,
efficiency of production and resource allocation, corporatization,
product quality, technical progress, and profitability.
Research conducted within this paradigm aims
to test whether certain industry characteristics
(for example, a small number of sellers) exert a stable influence on
the competitive strategies and the position of firms and buyers in the
corresponding markets (for example, the price level).
The microeconomic approach to analyzing the organization of industrial
markets began to be developed mainly by economists of the Chicago
school. One of the first proponents of the microeconomic approach, Stigler
G., even expressed the view that industrial organization economics does not
exist as a separate field of knowledge within economic theory, but simply
coincides with the conventional price theory in
microeconomics. This direction is based on the use of microeconomic
models and price theory.
The development of this approach is linked, on the one hand, to advances in the field of price
theory, and, on the other, to the availability of statistical
information at a more detailed microeconomic level. This
school explores the problem of choice faced by producing and
consuming economic agents.
An industry is often characterized as a set of enterprises
producing homogeneous products. In practice, however, classifying
enterprises under this criterion into industries is subject to considerable
deviations, since alongside the core product line there is also
a non-core one. Such a “contaminated” industry is called an administrative industry. As
a result, the concept of an industry as a set of enterprises diverges from
the concept of an industry as a set of producers of homogeneous products.
An industry as a set of single-product producers
dispersed across individual enterprises can be formed
artificially. Such industries are called “pure” industries.
A competitive industry (Industry) – the set of all producers
of a given product (or the set of sellers) that fully
substitute for one another. An industry implies enterprises united
by the output of interchangeable products, simultaneously competing
with one another in the marketing of these products. This definition
“brings” the industry closer to the market. This aspect is called the “competitive” aspect.
Given a certain “solidarity” among enterprises of the same industry,
the economics of the industry more often uses the term “rivalry” rather than
“competition”.
There are two types of international industries:
– a multinational industry – a set of national
industries. Competitive advantages in one of the countries are, to a
greater or lesser degree, independent of competition
on the world market;
– a global industry – one in which the strategic position
of competing firms in particular geographic or
national markets is strongly influenced by its position on the
world market. Firms belonging to a global industry
compete with one another throughout the world.
The differences between a market and an industry are based on the fact that a market
is united by the need it satisfies, while an industry is united by the nature of the technologies used. Equating an industry with a market is unacceptable –
the goods sold by enterprises of an industry may be more or less
close substitutes, but they may also be completely independent
goods.
The definition of a market is linked to the purpose of the study.
Any market – the set of sellers and buyers of a given good.
It is united by the need being satisfied: for one party – to buy, for the other –
to sell. Markets bring together goods that are close substitutes from
the standpoint of their buyers.
The industry approach examines one side of the market – supply, where
firms act as sellers. Industries bring together
goods that are close substitutes in production
(technologically), and accordingly bring together their producers. The market
is “broader” than the industry, since it includes sellers, producers, and buyers.
Several industries may serve a single market. On the other hand,
an industry is “broader” than a market, since it may serve a number of markets with one or
several types of products, and the products may be quite
far apart from one another.
To analyze the prices and output of a given good, it is more convenient to study
the market, while for studying opportunities for entering or exiting a market it is more convenient
to study the industry. A potential new producer is most likely
to belong to this same industry (although it may, perhaps, serve a different
market). This industry will remain a refuge for firms leaving
this market and switching to serve another one.
It is much harder to leave an industry than a market.
Several types of market boundaries should be distinguished: product
boundaries, reflecting the ability of goods to substitute for one another in
consumption, time boundaries, and local boundaries.
The necessary breadth or narrowness of the boundaries in each specific case
depends, first, on the characteristics of the good, and second, on the purposes of the analysis.
Thus, for a durable good the time boundaries of the market will be
much wider and less well-defined than for a good of current consumption.
The determination of the local boundaries of a market depends on the actual intensity
of competition among sellers on the national or world market, and on
the height of the barriers to entry into the regional market faced by “outside”
sellers.
The indicator of the change in revenue when price changes. Suppose the price
of good A has risen; how has the revenue of the producers
of this good changed? If revenue has increased (or, accordingly,
the sellers' additional profit is positive), the market is limited only to
good A. If, on the other hand, revenue has fallen (the additional profit
of producers is negative, or non-positive), a close
substitute exists, good B. Consequently, it is incorrect to speak of the market for good
A alone; good B must be sought, and the market for good A+B must be checked again. The dynamics
of the revenue and profit of producer firms during a sustained price increase
indicate the boundaries of the market. This is based on the principle of the direct
price elasticity indicator. With a sufficiently aggregated definition of the market,
demand in such a market should be fairly inelastic. In this case
an increase in sellers' price leads to an increase in their revenue.
Correlation of goods' prices over time. A positive correlation
in the movement of goods' prices over a long period of time (5-10 years)
indicates that the goods are stable substitutes, that
is, that they constitute a single market. This criterion is based on the concept
of cross-price elasticity. If goods A and B serve as close
substitutes, an increase in the price of good A leads to an increase in demand for good
B and, other things being equal, to an increase in the price of good B.
The geographic boundedness of the market. As a criterion for different territories belonging to a single geographic market, the following are identified:
identical conditions of competition, such as the interconnection of demand,
the presence of customs barriers, national (local) preferences,
differences (significant/insignificant) in prices, transport costs,
and the substitutability of supply.
Having identified the boundaries of the market, it is necessary to determine the firms producing
the good in this market. In doing so we will resolve an important question of the study -
the relationship between the market and the industry. How correctly the circle of
enterprises operating in our market has been defined should be verified with the help of
two indicators: the specialization index and the coverage index. Suppose we
are considering the production of good X by enterprises that we have assigned to
the corresponding industry (subindustry) X. In this case:
- the specialization index – the share of sales volume of good X in the total sales volume of enterprises that we have assigned to industry X;
- the coverage index – the share of sales volume of good X by enterprises that we have assigned to industry X, in the total sales volume of good X.
1. “Milk is a useful and important food product, and the milk market
– is one of the most important Russian food markets. Milk and
dairy products make up about 15 % of the minimum basket
of products that a person needs. World milk production has grown and
now amounts to approximately 675 million tons per year. The driving force in the industry
is good productivity and high world prices. This applies
to both developed and developing countries. In some countries of this group
growth in production is very high: 8 % – in Argentina, 18 % – in China, 3 % – in
Brazil, 3 % – in India. The EU's share in world trade in dairy
products is constantly declining. Ultimately, the EU may cede to
New Zealand its position as the largest exporter of dairy products
in quantitative terms”. What market (or markets) – according to all
classifications – is being discussed in this analytical excerpt?
2. Is competition possible and desirable in markets
for strategic raw materials? Give examples of more
competitive markets, and of more concentrated markets regulated by the
state, of this kind, in various countries. What can be
classified as strategic raw materials?
3. What standard industrial classifier is in effect in Russia? What is its distinctive feature? What are its main advantages and principal
shortcomings?
It is known that large Russian (Soviet) coal-fired thermal power plants were designed to be tied to specific coal enterprises
(they were built as close as possible in order to reduce the transport component), while Western European ones were tied to the consumer,
to a sea/river port, a railway station, taking the environmental factor into account, etc. What market, including energy
coal, would you identify in Russia and in Western Europe? What problems does each type of market give rise to?
1. The processes of market development in the «structure — conduct — performance» paradigm are determined by:
2. The basis of monopoly phenomena in the market is:
3. Can the elasticity index take negative values:
4. The main purpose of the methods and models for analyzing a commodity market is the preparation of:
5. The life-cycle concept is based on the hypothesis that there exist, for products and technologies, certain universal stages of development that determine the situation in the industry. Mark the stages that are correctly indicated in terms of composition and sequence:
6. The combination of companies from different industries linked by the technological process of producing a finished product is customarily referred to as:
7. At which stage of a product's life cycle is the market characterized by the highest exit costs (exit barriers):
8. Can a monopolist company control a market lacking entry and exit barriers:
9. According to the Chicago paradigm in the theory of industrial markets, discounts on goods are:
10. Industrial organization economics can be defined as the science:
11. Many of the questions examined in industrial organization economics are, at the same time, also the subject of:
12. At present, three main directions can be distinguished within the theory of the firm:
13. The agents of an industrial market:
14. An industry — is:
15. The market concentration of sellers of a good reflects:
16. A single seller in the market, with no close substitute products for the good — this is:
17. A price that changes rapidly under changing conditions of demand and supply — this is:
18. How does a firm differ from other economic entities:
19. Why does a firm purchase resources:
20. A horizontal boundary is:
21. What determines the horizontal size of a firm:
22. The strategy of a firm — is:
23. The size of a firm is assessed by:
24. By form of ownership, a firm is divided into:
26. By corporate-legal form, a firm is divided into:
27. A linear management sequence is:
28. The functional form of a management sequence is:
29. The staff (headquarters) form of a management sequence — is:
30. A holding company is:
31. Franchising is:
32. A franchisee is:
33. A franchise is:
34. A media franchise – is:
35. A franchisor — is:
36. Transaction costs — are:
37. Control costs — are:
38. The higher the transaction costs relative to the control costs, the higher the probability that the good will be produced by:
39. A firm, as a separate subject of economic activity, exists between two types of costs:
40. The strategic concept of the firm — is:
продолжение следует...
Часть 1 Industrial Organization: Scientific Approaches to the Analysis of Industry Markets

Comments